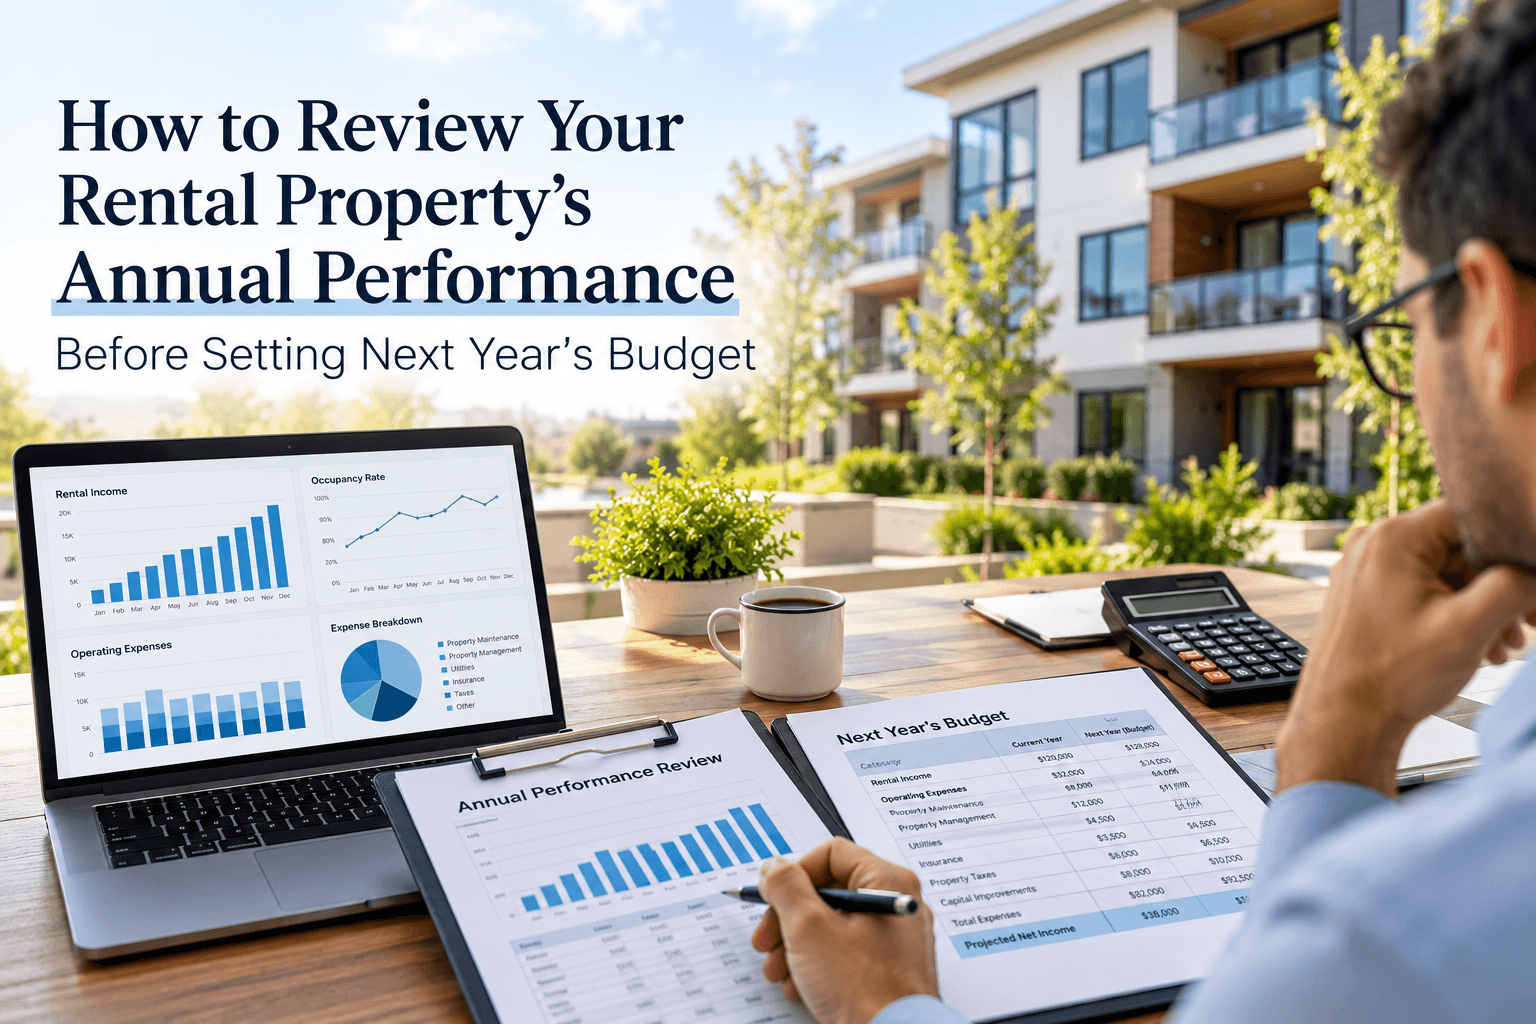
A rental can collect nearly every payment due and still leave its owner short of cash. A property tax increase, a vacant month and an aging HVAC system may not show up in the rent figure, but they belong in next year’s budget.
Before choosing a maintenance allowance or deciding whether to raise rent, look at what the property actually earned, spent and needed over the past twelve months. Use those findings to change the forecast, rather than copying last year’s budget and adding a percentage.
Start With Records You Can Reconcile
Collect the year’s rent ledger, bank deposits, mortgage statements, invoices, property tax bills, insurance notices and any statements from your property manager. If you own several rentals, review them individually before looking at portfolio totals. One profitable Fairfax home can conceal an expensive year at a property in Rockville.
Match rent recorded as received against deposits. Check whether management fees were deducted before funds reached your bank account. Identify tenant reimbursements, returned payments and any security deposits mistakenly included as income. Check vendor bills paid by the manager against invoices and include expenses you paid directly, outside the management account. A security deposit generally isn’t rental income when you expect to return it; the IRS explains the exceptions.
Measure the Rent You Could Have Earned Against What Arrived
Take the monthly rent under each lease and calculate the amount scheduled for the year. Then compare it with rent actually collected.
Suppose your Alexandria rental was priced at $2,500 per month. Twelve occupied, fully paid months would produce $30,000. If it stood empty for one month between tenants and every other payment arrived, you collected $27,500. That $2,500 difference is vacancy loss, not unpaid rent.
Make the distinction. Vacancy points you toward renewal timing, turnover speed or asking-rent decisions. Late or missed payments call for a different review of collection practices and tenant accounts. Concessions should also appear separately; a discounted first month is not a maintenance expense.
Look at your lease expiration date before projecting next year’s rent. Compare current listings and recently leased homes with similar location, size and condition. A Reston townhouse and a D.C. apartment shouldn’t share a blanket rent-growth assumption. Any planned increase also needs to fit the lease and applicable local rules.
Find Out Which Costs Will Follow You Into Next Year
Annual totals are useful, but individual invoices explain more. Sort expenses by their likely behavior:
- Recurring commitments: insurance, property taxes, HOA or condo dues, management charges and contracted services.
- Variable operations: routine repairs, landscaping, utilities paid by the owner and seasonal maintenance.
- Major, irregular work: an HVAC replacement, substantial flooring work or another project that shouldn’t be treated as an ordinary monthly bill.
Now compare each group with last year’s budget and the previous year’s actual results, if available.
A $3,200 water-heater replacement might explain most of this year’s overspend. Repeating that amount automatically in next year’s repair allowance would distort the forecast. But three plumbing callouts for the same recurring leak suggest a problem worth investigating and budgeting to fix.
Watch costs that rise quietly. An insurance renewal or HOA assessment can change next year’s cash needs without a single new maintenance request. Use actual notices and quotes wherever possible. For pending increases, label your estimate so you know which figure to revisit.
Keep capital improvements separate from routine repairs, both for budgeting and recordkeeping. The IRS distinguishes repairs from improvements, and their tax treatment can differ. Your tax return also isn’t a substitute for a cash budget.
Calculate What the Property Really Produced
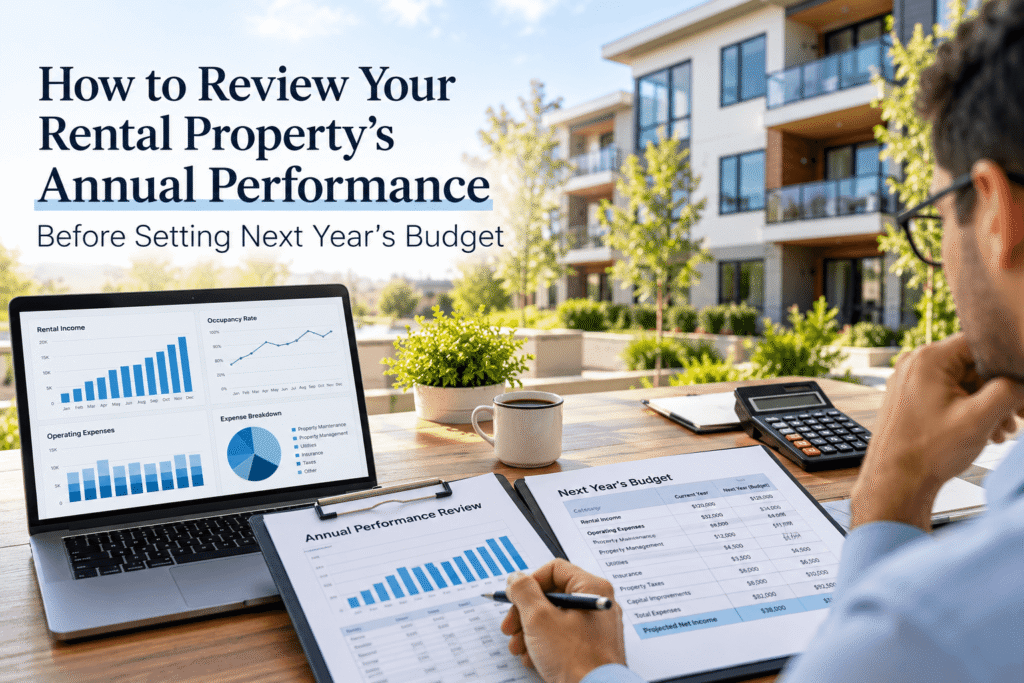
Here’s an illustrative annual review for that $2,500-a-month rental:
Performance measure | Year-end result |
Potential rent at full occupancy | $30,000 |
Rent actually collected | $27,500 |
Operating expenses | $8,100 |
Net operating income | $19,400 |
Mortgage payments (principal and interest) | $15,600 |
Capital work paid during the year | $1,900 |
Cash remaining before income taxes | $1,900 |
Net operating income (NOI) is rental income minus operating expenses. It excludes mortgage payments, income taxes and capital expenditures. For an owner evaluating cash available, those payments still matter. Mortgage principal reduces debt, but paying it leaves less cash in the bank.
Don’t mistake the $19,400 NOI for spendable profit. In this example, only $1,900 remained after the listed payments. An additional vacancy or expensive repair could absorb that quickly. If you funded reserves separately, include those transfers when reviewing available cash.
Let the Results Set Next Year’s Budget
The next budget needs an assumption beside every meaningful number. For rent, use expected lease rates, realistic occupied months and any concessions. For fixed bills, use renewal quotes and published assessments. For routine maintenance, use the property’s condition and its repair history, not a generic percentage copied from another house.
Then make room for known work. If an inspection found a deteriorating deck or the furnace is near the end of its useful life, obtain estimates and decide when the expense is likely to occur. Separate committed projects from a reserve for surprises.
Stress-test the forecast before approving it. What happens if the property loses another month of rent? Could it absorb a $2,000 repair without requiring an unexpected owner contribution? If the answer is no, adjust spending plans or build a larger cash reserve before counting on distributions.
You may find that the right decision isn’t a rent increase. It could be renewing a reliable tenant earlier, addressing recurring repair problems or delaying an optional upgrade.
Give the Budget a Review Date
A year-end budget loses value if nobody checks it until the following December. Compare actual rent, spending and cash balance with the forecast quarterly, and revise when a tax assessment, lease renewal or major repair changes the picture.
For owners who want help organizing the operational side, Elevate Realty Solutions’ landlord services include rental oversight and maintenance coordination across Northern Virginia, Maryland and Washington, D.C.
Set aside that reserve before deciding how much rental cash to withdraw.